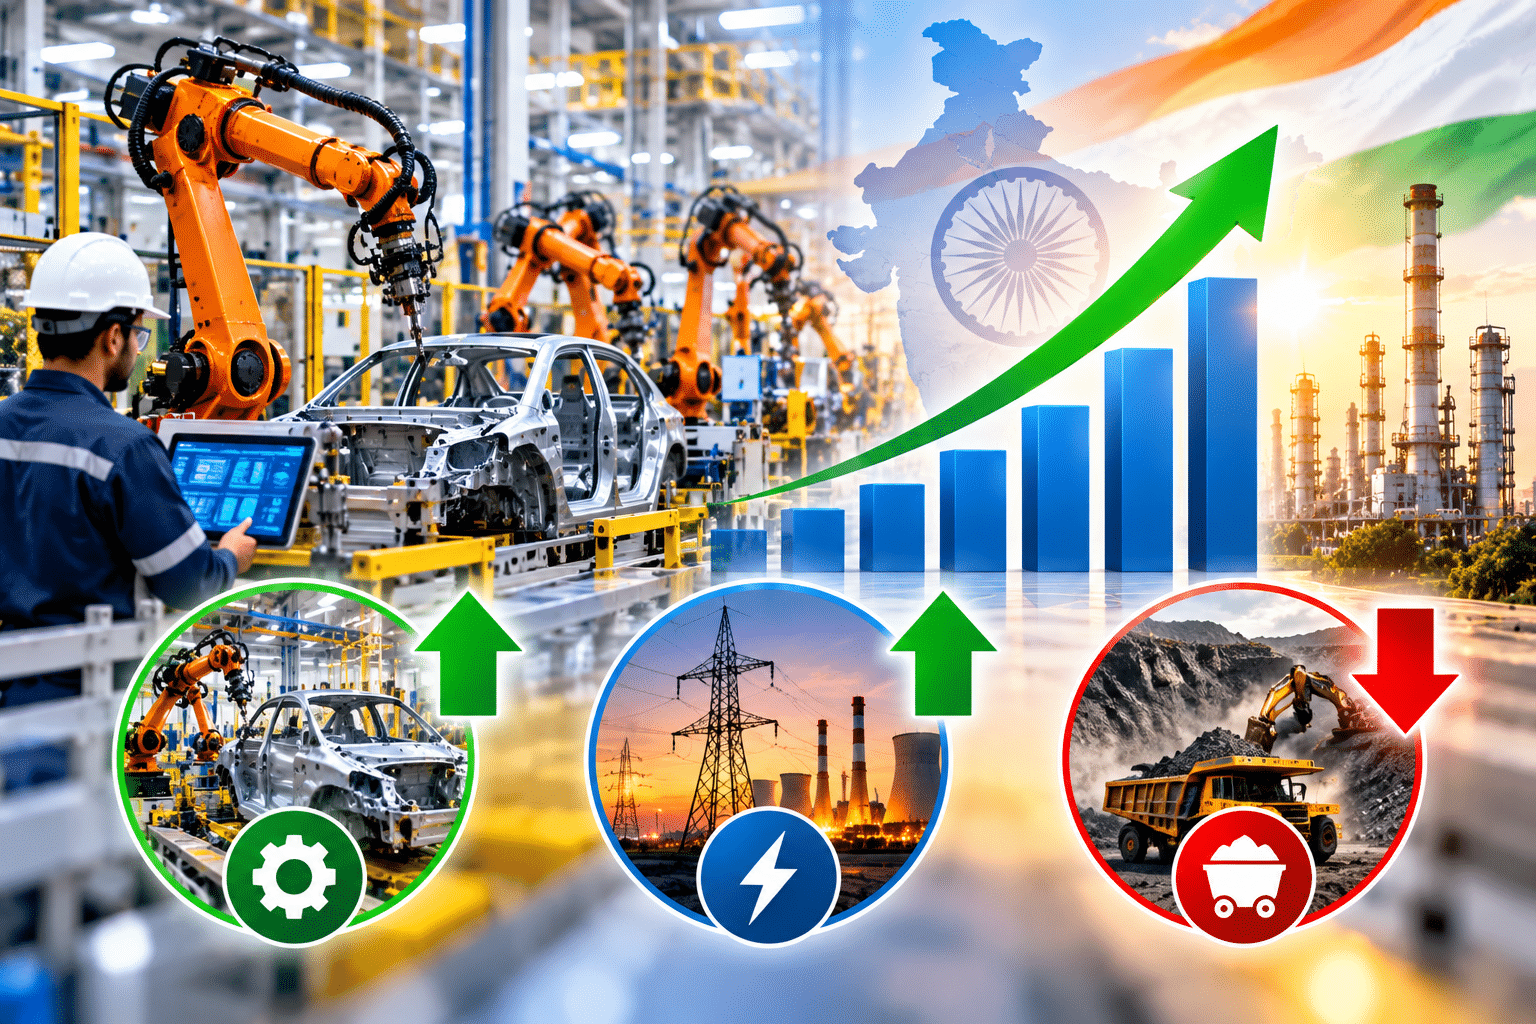
India’s industrial growth moderated to 6.7 per cent year-on-year in September 2026, down from a revised 7.8 per cent in August. According to official data released by the National Statistics Office (NSO), the slowdown was primarily driven by a deepening contraction in mining activity and a slight easing in manufacturing expansion.
Despite the sequential moderation, industrial production maintained resilient momentum overall. Specifically, the Index of Industrial Production (IIP)—which now utilises 2022-23 as its base year—expanded 6.8 per cent across the first half of FY27 (H1 FY27).
                 SEPTEMBER 2026 IIP SECTORAL BREAKDOWN

    +-----------------------------------------------------------+
    |            Overall Industrial Growth (IIP)                |
    |                         (+6.7%)                           |
    +-----------------------------+-----------------------------+
                                  |
            +---------------------+---------------------+
            |                     |                     |
            v                     v                     v
+-----------------------+ +-----------------------+ +-----------------------+
| Manufacturing         | | Electricity & Gas     | | Mining & Quarrying    |
| - Growth: +7.6%       | | - Growth: +11.2%      | | - Contraction: -6.2%|
| - Weight: ~76%        | | - Strong Utility Demand| | - Drag on Raw Materials|
+-----------------------+ +-----------------------+ +-----------------------+
Sectoral Drivers: Mining Drag vs Utility Strength
Mining and quarrying remained the primary drag on overall industrial performance, with output contracting 6.2 per cent in September following a 4.6 per cent decline in August. Because the sector supplies critical raw materials to steel, cement, and power generation, persistent weakness raises concerns regarding industrial input availability.
Conversely, manufacturing—which constitutes nearly 76 per cent of the IIP basket—grew 7.6 per cent in September compared with 8.6 per cent in August. Within manufacturing, 17 out of 23 industry groups recorded expansion, led by motor vehicles, electrical equipment, and rubber products. Meanwhile, electricity and gas supply posted a robust 11.2 per cent expansion.
Use-Based Classification Points to Capital Investment
From a use-based perspective, capital goods registered a double-digit expansion of 10.4 per cent, while intermediate goods grew 12.2 per cent. These figures indicate sustained momentum in investment-linked industries and corporate capital expenditure.
However, consumer non-durables grew by just 1.4 per cent, signaling that production of fast-moving daily consumer goods remains relatively subdued. Infrastructure and construction goods expanded 7.2 per cent, reflecting steady public capital spending.
High Base Effect and Festive Outlook
Economic analysts attribute the moderation largely to a statistical high-base effect alongside pre-festive stock inventory adjustments made during August. Furthermore, elevated raw material input planning and inflationary pressures led manufacturers to calibrate production schedules.
Looking ahead, economists project IIP growth to rebound in October 2026 to between 8 and 9 per cent, supported by peak festive season consumer demand and favorable base comparisons across manufacturing and power generation.
Takeaways
While headline economic figures present an optimistic picture of domestic expansion, an analytical examination of recent data highlights significant structural trade-offs. Beneath the surface, key industrial segments, consumption patterns, and financial markets exhibit growing divergence.
Consequently, policymakers and corporate boards face distinct vulnerabilities that could constrain long-term productivity if left unaddressed.
The September IIP moderation to 6.7 per cent masks a severe operational bottleneck in primary extraction. Specifically, the mining and quarrying sector contracted by 6.2 per cent, deepening its previous month’s decline.
Because mining provides foundational inputs for steel, power, and cement, persistent declines threaten industrial supply chain stability. Furthermore, while public sector capital expenditure continues to drive capital goods growth (10.4 per cent), private sector balance sheets remain cautious about undertaking large-scale, greenfield investments.
+--------------------------------+-------------------------------------------------------+
| Policy Sector                  | Critical Structural Risk & Disconnect                 |
+--------------------------------+-------------------------------------------------------+
| Industrial Extraction          | Deepening mining contraction (-6.2%) threatens inputs |
| Consumer Non-Durables          | Subdued growth (+1.4%) indicates persistent K-recovery|
| Capital Market Outflows        | Secondary market FPI sell-off exceeds ₹53,000 crore   |
| Renewable Integration          | Grid curtailment risks amidst rapid solar capacity    |
+--------------------------------+-------------------------------------------------------+
A persistent challenge lies in the stark gap between luxury and mass consumption. The September IIP data reveals that consumer non-durables—representing fast-moving daily goods—grew by a modest 1.4 per cent.
In contrast, consumer durables expanded by 6.0 per cent, fueled by urban middle-class replacement cycles and credit availability. Thus, real wage growth across rural and informal sectors continues to lag, creating a two-speed consumption economy that limits broad-based growth.
Meanwhile, in capital markets, secondary equity sell-offs by Foreign Portfolio Investors (FPIs)—exceeding ₹53,000 crore in October—highlight vulnerability to global macroeconomic shocks. Elevated crude oil prices and tightening global monetary conditions frequently trigger rapid foreign capital flight.
Simultaneously, regulatory efforts by SEBI to curb retail speculation in derivatives and enforce strict cybersecurity measures impose higher compliance burdens on smaller brokerages. Consequently, smaller market intermediaries face consolidation risks, even as regulators push to expand access into Tier-2 and Tier-3 towns.
Rapid capacity additions in the green energy space—exemplified by massive utility-scale solar module deployments in Rajasthan—face severe transmission bottlenecks. Without commensurate investments in battery energy storage systems (BESS) and high-voltage grid upgrades, aggressive solar additions risk high curtailment rates.
Ultimately, navigating these structural frictions requires moving beyond aggregate target metrics. Therefore, policy attention must balance headline capacity targets with systemic grid resilience, input supply security, and equitable wage expansion.
About The Author
