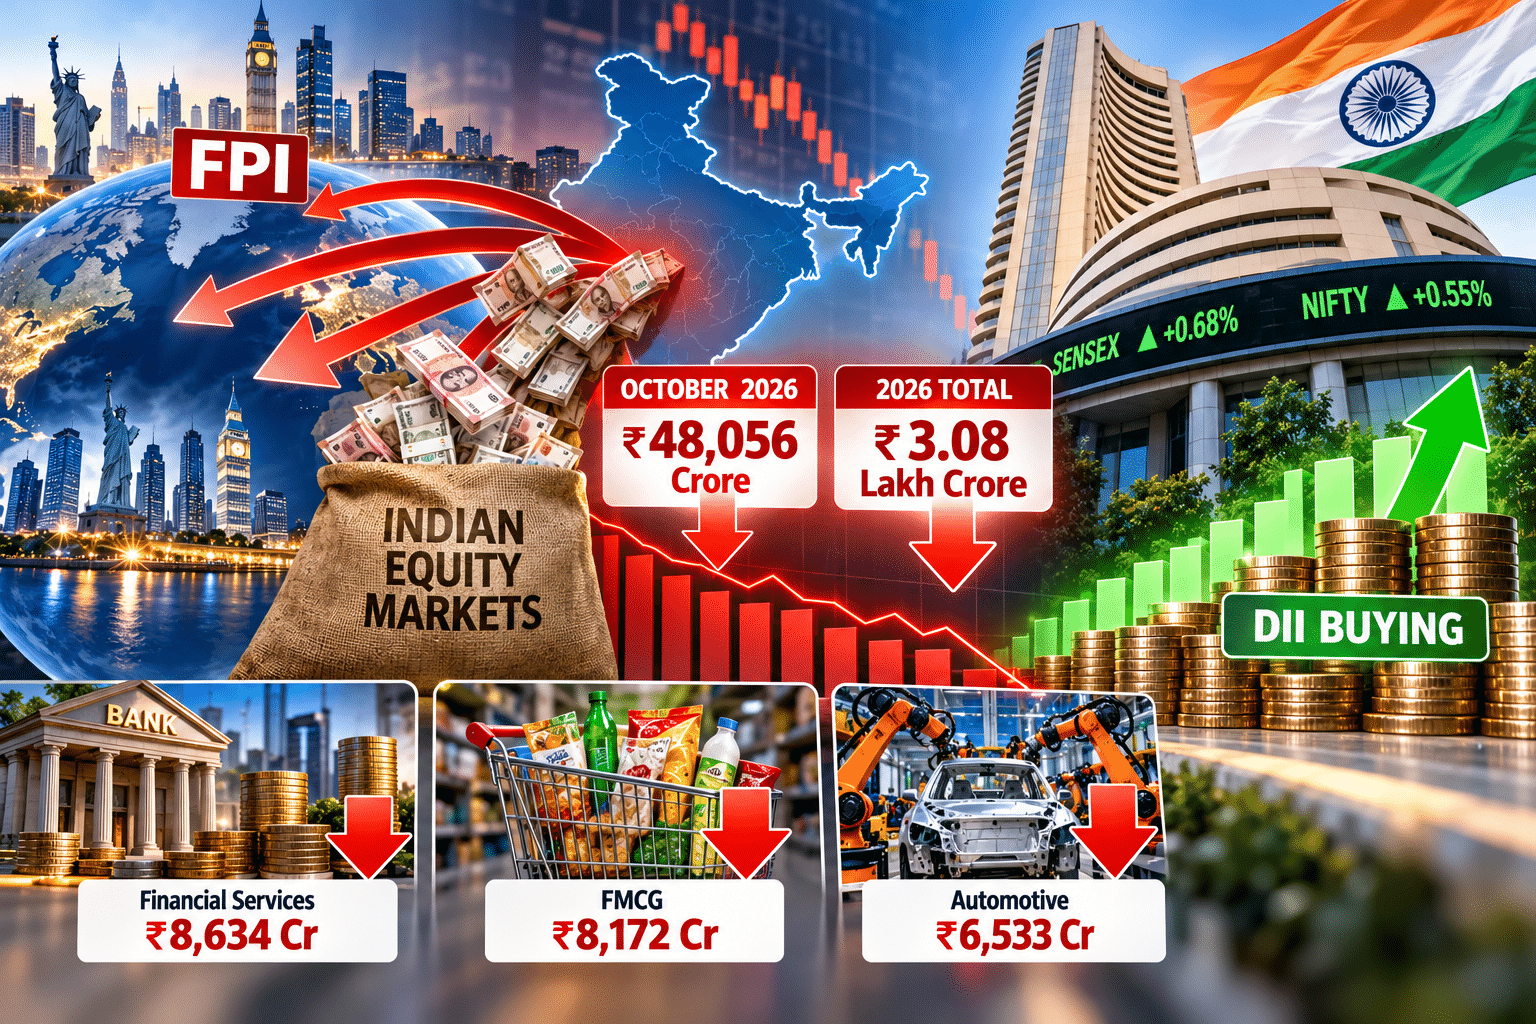
Official transactional statistics from Central Depository Services Limited (CDSL) regarding equity outflows confirm that Foreign Portfolio Investors (FPIs) accelerated their exit from Indian equity markets during October 2026. Overseas funds recorded net equity sales of ₹48,056 crore over the month.
Consequently, cumulative FPI equity outflows for calendar year 2026 reached an unprecedented ₹3.08 lakh crore. Depository records maintained by NSDL highlight that net secondary market foreign equity sales surpassed ₹3.64 trillion ($38.69 billion) by mid-October.
              2026 FPI CAPITAL OUTFLOW TRAJECTORY (CDSL DATA)

    +-----------------------------------------------------------+
    |             Cumulative 2026 FPI Equity Outflows           |
    |                   (₹3.08 Lakh Crore Net Sales)            |
    +-----------------------------+-----------------------------+
                                  |
            +---------------------+---------------------+
            |                                           |
            v                                           v
+-----------------------+                   +-----------------------+
| October Pullback      |                   | September Pullback    |
| - ₹48,056 Crore Net   |                   | - ₹35,861 Crore Net   |
|   Withdrawal          |                   |   Withdrawal          |
+-----------------------+                   +-----------------------+
Equity Outflows Across Financials and FMCG
Official fortnightly sector disclosure reports published by primary depositories detail broad-based selling across blue-chip indices. During the first half of October alone, financial services recorded the largest foreign net outflow at ₹8,634 crore ($908 million).
Simultaneously, Fast-Moving Consumer Goods (FMCG) faced net foreign selling of ₹8,172 crore ($860 million), while automotive sector equities saw withdrawals of ₹6,533 crore ($687 million).
+--------------------------------+-------------------------------------------------------+
| Depository Metric (CDSL/NSDL)  | Financial Value & Sector Breakdown                    |
+--------------------------------+-------------------------------------------------------+
| October FPI Net Equity Sales   | Net Outflow of ₹48,056 Crore                          |
| Cumulative 2026 FPI Outflows   | ₹3.08 Lakh Crore (Vs ₹1.66 Lakh Crore in CY 2025)     |
| Top Sectoral Sell-off (Oct)    | Financial Services (-₹8,634 Cr), FMCG (-₹8,172 Cr)    |
| DII Counter-Absorption (CY26)  | Domestic Mutual Funds Net Bought Over ₹6.83 Trillion  |
+--------------------------------+-------------------------------------------------------+
Global Yield Differentials and Valuation Disconnects
International portfolio managers cite widening bond yield differentials and elevated Price-to-Earnings (P/E) multiples on Indian stock exchanges as major catalysts. Higher yields on US Treasury securities offer attractive risk-adjusted returns without exposure to emerging market currency fluctuations.
Furthermore, volatile Brent crude oil prices threaten India’s current account deficit and corporate operating margins. Consequently, global funds are reallocating equity allocations toward cheaper Asian equities and Western debt instruments.
The Domestic Liquidity Cushion Masking Structural Vulnerability
Despite record foreign selling, benchmark indices avoided catastrophic crashes due to unprecedented Domestic Institutional Investor (DII) buying. Data indicates DIIs absorbed most of the foreign supply, deploying over ₹6.83 trillion ($72 billion) across 2026 through retail Systematic Investment Plans (SIPs).
However, market analysts warn that depending entirely on domestic liquidity masks underlying valuation risks. If earnings growth moderates in upcoming quarters, retail SIP inflows could slow down, leaving secondary markets vulnerable to deeper price corrections.
About The Author
